Financing an engagement ring means paying for a ring over time, often in monthly payments, instead of paying the full price upfront. Many jewelry stores offer engagement ring financing (and credit cards and personal loans are also an option) — but to avoid overpaying, make sure you thoroughly understand your monthly payment, total cost, interest, fees, and payoff timeline.
How to finance an engagement ring without overpaying:
- Decide how much to spend on an engagement ring and set a maximum ring budget.
- Decide how much cash to put down.
- Compare your financing options.
- Calculate your total interest and fees.
- Choose the lowest-risk payment plan.
- Protect your new ring with insurance coverage after your purchase.
With some guidance from Boonville, Missouri, jewelry consultant Nicole Strong, let’s explore your financing options and how to make the smartest financial decision possible.
What You Will Learn
- What Does It Mean to Finance an Engagement Ring?
- How Much Should You Finance for an Engagement Ring?
- Paying Cash Vs. Financing the Ring
- Credit Card Financing
- Jewelry Store Financing
- Personal Loans for Engagement Rings
- Buy Now, Pay Later and Layaway Plans
- How to Choose the Best Financing Option
- Build a Financing Plan Before You Buy
- Step-by-Step: How to Finance an Engagement Ring
- Financing Risks, Fees, and Fine Print to Watch For
- After You Finance the Ring, Protect the Purchase
- Engagement Ring Financing FAQs
- Conclusion: Finance the Ring Only if the Plan Starts on the Right Foot
What Does It Mean to Finance an Engagement Ring?
Financing an engagement ring means using payment options such as a credit card, loan, store plan, or layaway to purchase or reserve an engagement ring now, while paying for it over time.
If you purchase the ring using traditional jewelry financing options — like a store plan or credit — you can take the ring home immediately. If you opt for store layaway, however, the store keeps the ring until you’ve completely paid for it, over a set number of installments.
A store plan or credit-based option may charge interest, but layaway does not.
How Much Should You Finance for an Engagement Ring?
Avoid financing the full price of the ring by default; instead, make a down payment of whatever you reasonably can afford upfront, and then finance the remainder of the ring’s cost.
Amount to finance = Ring price − Down payment
Be sure to consider the resulting loan amount and how it will affect your monthly budget.
A safe monthly payment = The amount you can pay consistently without disrupting rent, bills, debt payments, wedding savings, or emergency savings.
| Ring Price | Down Payment | Amount Financed | Monthly Payment to Consider |
|---|---|---|---|
| $3,000 | $500 | $2,500 | Calculate based on term/APR |
| $5,500 | $1,000 | $4,500 | Calculate based on term/APR |
| $10,000 | $2,000 | $8,000 | Calculate based on term/APR |
According to The Knot’s 2026 Real Weddings Study, the average engagement ring cost is $4,600, but set your ring budget at whatever price feels most comfortable for your unique financial situation, especially if you plan to finance the ring.
Paying Cash Vs. Financing the Ring
Paying cash for the engagement ring in one lump sum helps you avoid interest and debt, but financing the ring can ensure you don’t have to dip into your savings, while also making a large purchase more manageable, spreading it out over time.
| Payment Method | Best For | Downside |
|---|---|---|
| Paying cash | Buyers who can afford the ring without draining their savings | May reduce your available emergency cash |
| Partial cash + financing | Buyers who want lower monthly payments | Requires discipline to pay off the remaining balance and may require an application process |
| Full financing | Buyers without upfront cash | Interest or fees may apply |
Ultimately, you don’t want to finance a ring if the monthly payment would strain your budget or increase the pressure you’re already feeling from existing debt. Once you’ve decided on a financially healthy path forward, check out BriteCo’s ultimate engagement ring buying guide for ring ideas within your budget.
Credit Card Financing
Advice on buying an engagement ring will tell you that doing so with a credit card can be a good idea if: (1) you already know how you’ll pay off the debt, (2) your credit limit can cover the cost of the ring, and (3) you are able to get a zero-interest credit card.
By opting for a new credit card with zero interest, you can avoid interest charges and only pay for the ring itself. (It’s even better if the card offers purchase protection or rewards!)
Before Buying a Ring on a Zero-Interest Credit Card
- Confirm that the promotion truly does include zero interest for a set time period.
- Note when the promotional period ends.
- Divide the balance you’ll put on the card, for the ring, by the months within the promotional period, to get the minimum amount you’ll need to pay monthly to avoid interest.
“You can have it planned out to have it paid within that time frame. Then you’re golden,” Strong says. “But those do tend to, after that time frame, carry a lot of interest or carry the back interest from the six months or 90 days when you haven’t been paying interest if you do let it go past those terms. Once you get hit with that interest, it’s going to be a lot higher than it would with most other cards,”
Once you’ve purchased the ring, set up automatic payments for the card, in payments above that minimum amount. Avoid making any other charges to that card, if it risks not being able to pay it off before the promotional period ends. If the balance is not paid off before the promotional period ends, the resulting interest can make your engagement ring cost significantly more.
Jewelry Store Financing
When you buy an engagement ring online or at a jewelry store, many jewelers and online jewelry brands will offer you a financing plan via partner lenders or a branded credit card.
These plans may advertise competitive interest rates or no interest for a promotional period, but always check the fine print regarding the promotional APR, deferred interest, minimum payment requirements, retroactive interest, late-payment penalties, account-opening fees, and whether or not the promotion will actually apply to your specific purchase.
Not doing so can result in you paying high interest rates regardless, or extra fees that increase the total cost of your ring.
Before signing up for jewelry store financing:
- Read the fine print.
- Ask what happens if the balance is not paid in full within the promotional period.
- Ask whether interest is waived or deferred.
- Get the final payoff date in writing.
Personal Loans for Engagement Rings
A personal loan will come with a fixed loan amount, fixed repayment terms, and a predictable payment schedule, making this an attractive option for buyers who want structure and who may not qualify for a strong, zero-percent credit card.
| Personal Engagement Ring Loan Pros and Cons | |
|---|---|
| Pros | Cons |
| Fixed rates make it easier to calculate your total cost | If the loan doesn’t require collateral, the ring may not be directly pledged |
| Fixed repayment terms come with clear payoff dates | More interest can make the ring more expensive than if you paid with cash |
| Prequalification processes allow you to compare your options before committing | |
As an engagement ring might not be deemed an essential purchase, “I’m not sure how banks would feel about lending toward that unless you have good personal credit from the get-go,” Strong says. ”And some banks don’t lend smaller amounts. So if you’re under, like, $5,000 for your engagement ring, they might not want to worry about that loan.”
Before committing to a personal loan for an engagement ring, make sure the payments will fit your budget and financial situation.
Buy Now, Pay Later and Layaway Plans
Buy now, pay later (BNPL) payment plans and layaway are two additional flexible payment options to consider for an engagement ring — BNPL is useful for quickly repaying your debt, if you’re confident you can do so, but layaway is generally safer if you want to avoid debt altogether, and don’t mind waiting until the ring is paid for, to take it home.
| Jewelry Financing Options | How It Usually Works | Downside |
|---|---|---|
| Buy now, pay later | Buyer gets the ring now and pays for it in installments | There may be missed-payment fees, and BNPL can impact your credit |
| Layaway | Jeweler holds the ring while buyer pays for it over time | The ring may not be released until it’s paid for in full |
| Store payment plan | Buyer follows jeweler/lender terms | Promotional details vary; you may have to make minimum monthly payments, for example |
“Rings are kind of special in that they’re one of the few things that you can still buy on layaway,” Strong says. “Unless you need to build credit or something, I would go that route because you don’t have any interest usually with those sorts of plans.
“A lot of times nowadays, couples like to design their own engagement rings. So you’re going to have a process time there anyway where you’re not going to have the ring in your hand from day one. If you have the time to do it, I would go with layaway.”
How to Choose the Best Financing Option
The best engagement ring financing option for you will depend on your unique financial situation, including your credit profile and credit score, available cash, how soon you want to pay off the ring, and your tolerance for financial risk.
| If this is true… | Consider… | Why? |
|---|---|---|
| You can pay the ring off within a certain time period | A 0% credit card or promotional plan (just be sure to pay off the ring within that promo period!) | With a zero interest rate promotion, this is your most affordable option |
| You want predictable payoff terms | A personal loan | They come with easy, fixed payments and terms |
| You do not want debt | Using layaway or simply saving up more cash | You’ll avoid interest |
| Your credit is weak | Saving cash to purchase the ring or buying a more affordable ring | You’ll avoid high-cost financing |
“For younger couples, I might suggest a personal credit card or store financing because they might be in that spot where they need to build some personal credit,” Strong says. “They can build up their credit with this bigger purchase at the beginning of their marriage.”
If you need the ring soon, compare financing offers quickly, but don’t rush into bad terms.
Additionally, always compare the end, total cost of financing an engagement ring, inclusive of interest and fees. Don’t be swayed by a deceptive low monthly payment. Always ask for the fine print before committing — don’t worry, you won’t be committing any engagement ring shopping etiquette faux pas by doing so.
Build a Financing Plan Before You Buy
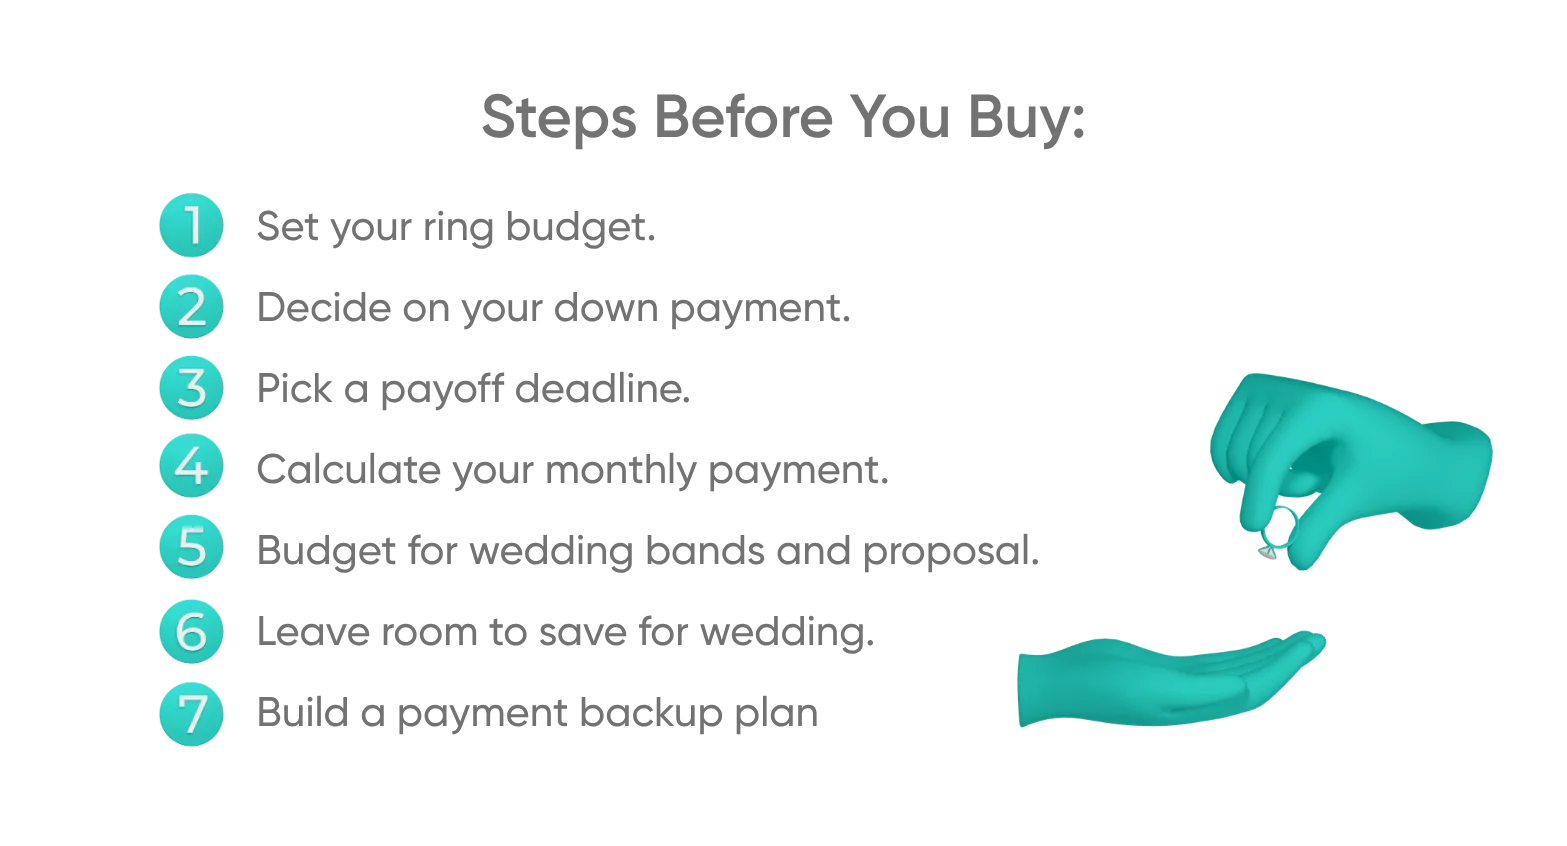
Careful planning is key to making a financially wise decision regarding your engagement ring purchase. As you plan the perfect proposal, keep in mind: Your engagement ring will be the first of many future purchases ahead, with an entire wedding on the horizon.
Step-by-Step: How to Finance an Engagement Ring
- Choose a realistic maximum ring price.
- Decide how much cash to put down.
- Check your credit and correct any errors.
- Compare credit cards, jewelers’ offers, personal bank loans, BNPL, and layaway offers.
- Calculate your total cost with interest and fees.
- Read the financial institution’s contract before signing.
- Confirm payment due dates.
- Buy the ring.
- Save the receipt, financing agreement, appraisal, and ring details.
- Protect the ring after purchase with engagement ring insurance.
Financing Risks, Fees, and Fine Print to Watch For
Don’t inadvertently choose a financing option that looks affordable at first glance, but that will actually cost you more later — look for the following red flags and signs of a bad deal:
- Deferred interest charges
- Late fees
- Origination fees
- Balance transfers fees
- Prepayment penalties
- Required minimum purchase amounts
- Balloon payments
- Variable interest
- Credit utilization impact
- Missed-payment credit damage
If the financing only looks affordable because your monthly payment is low, do the math and calculate your overall total cost before signing. You may need to wait a bit longer to propose. (How soon is too soon to propose? We can’t weigh in on your relationship, but if you can’t afford the ring, it might be too soon.).
After You Finance the Ring, Protect the Purchase
Once you’ve purchased the right ring and decided on financing, you may still end up owing money you didn’t expect, because, without the right protection, you could find yourself making this large purchase all over again if the ring is ever lost, stolen, or damaged
Documentation, insurance coverage, and secure storage are crucial.
- Save your receipt and financing agreement.
- Acquire or request appraisal documentation.
- Photograph the ring and keep those photos with your other documentation.
- Store the ring safely before and after the proposal.
- Review your engagement ring insurance options.
- Then, start saving for your future wedding bands!
Make a smart choice and learn how to insure an engagement ring before you get that ring home. The best ring insurance comes with zero deductibles, easy monthly payments, and coverage of up to 125% of the ring’s appraised value.
Engagement Ring Financing FAQs
Is it Normal to Finance an Engagement Ring?
Yes, it’s quite normal to finance an engagement ring rather than pay for it in full at the time of purchase, whether that means getting a loan, using a credit card, or using a store payment plan.
Is a 0% Credit Card Good for Buying an Engagement Ring?
A 0% credit card can be very good for buying an engagement ring, so long as you pay off the ring within the promotional period. Otherwise, the ring will ultimately cost you more, as you pay interest until it’s paid off.
Should I Insure a Financed Engagement Ring?
Yes, you should always insure your engagement ring. When you spend thousands of dollars on a piece of jewelry — no matter if you paid cash or financed — you want that jewelry to be protected. When you see how much engagement ring insurance costs — 0.05-1.5% of the ring’s total value — you’ll quickly realize it’s a smart investment in your ring’s security.
How Much Should You Finance for an Engagement Ring?
Consider how much cash you can comfortably pay for the ring. Subtract that amount from the ring’s cost and use it as a down payment. Then, finance the remainder.
Do Jewelers Finance Engagement Rings?
Yes, many jewelers offer in-store promotions for engagement ring purchases.
Conclusion: Finance the Ring Only if the Plan Starts on the Right Foot
Financing an engagement ring can be a smart choice, but you must know the monthly payment, total cost, payoff date, and contract terms before moving forward — no matter if you opt for a credit card, personal loan, payment plan, or any other financing option.
The smartest way to finance an engagement ring is to choose the ring and the repayment plan together — because the best ring is one that fits both your proposal vision and budget.
Then, protect your ring and get a quick, online engagement ring insurance quote now.
Appraisal Tool:
Sign Up for FREE Jewelry Appraisal Software for Jewelers
UP NEXT: December is Proposal Season: What the Data Says About Holiday Engagements
Author