Watch Insurance
Protect your watch with BriteCo coverage.
Get a quote in seconds and coverage in minutes.
Protect your watch with BriteCo coverage.
Get a quote in seconds and coverage in minutes.
Watch insurance from BriteCo covers theft, loss, mysterious disappearance, and accidental damage, with worldwide protection. If a covered event happens, BriteCo pays to repair the watch when it can be repaired, or replaces it at the insured value when it cannot.
A standalone policy from BriteCo covers the things that actually happen to watches:
Dropped, cracked crystal, water damage from exceeding depth rating, movement damage from impact
Including from your home, your car, or while traveling
You had it, now you don’t, no explanation required
Fell off your wrist, left in a hotel room, gone
When a covered event happens, BriteCo pays for repair if the watch is repairable, or replacement at the insured value if it’s not. A scratched bezel gets repaired. A crushed case gets replaced.
BriteCo watch insurance is a standalone policy covering theft, loss, mysterious disappearance, and accidental damage worldwide, with zero deductibles and no maximum insured value. Premiums run about 1% to 2% of insured value per year, roughly $150 to $300 for a $15,000 watch. Learn more about coverage
Get covered in under 2 minutes with worldwide protection for theft, loss, mysterious disappearance, and accidental damage. File claims online with ease, providing details of the incident, and a claims coordinator will get in touch to guide you through the process.
Submit a few basic details about your watch and get a quote within minutes.
Most BriteCo policies go into effect immediately.
Upload your watch appraisal/receipt, a photo, and gemological certificates if available.
Unlike homeowners riders, BriteCo claims aren’t reported to CLUE or A-Plus, so your homeowners insurance premiums aren’t affected.
Disclaimer: Coverage is subject to standard underwriting review and approval.
BriteCo premiums run around 1–2% of your watch’s appraised value per year. For a $15,000 watch, that’s roughly $150–$300 annually.
Two factors move the price most:
Refer to the pricing table for example estimates across common models. Unlike other specialized watch insurance providers, BriteCo policies carry zero deductibles.
BriteCo premiums run around 1–2% of your watch’s insured value per year. Here’s what that looks like across common models:
| WATCH | COVERAGE AMOUNT* | LOW-END COST/YR | HIGH-END COST/YR |
|---|---|---|---|
| Tudor Black Bay 58 | $4,150 | $50.00 | $73.21 |
| Omega Seamaster Diver 300 | $5,900 | $66.63 | $104.08 |
| Omega Speedmaster Professional | $7,600 | $85.83 | $134.06 |
| TAG Heuer Carrera | $5,750 | $64.94 | $101.43 |
| Rolex Datejust | $9,500 | $107.29 | $167.58 |
| Cartier Santos de Cartier | $7,750 | $87.52 | $136.71 |
| Breitling Navitimer | $8,680 | $98.03 | $153.12 |
| Rolex Submariner | $9,100 | $102.77 | $160.52 |
| IWC Big Pilot | $12,900 | $145.68 | $227.56 |
| Rolex GMT-Master II | $22,500 | $254.00 | $396.75 |
| Rolex Daytona | $32,000 | $361.39 | $564.48 |
| Cartier Tank Française | $19,100 | $215.65 | $336.83 |
| Vacheron Constantin Overseas | $25,500 | $287.91 | $449.69 |
| Audemars Piguet Royal Oak | $48,000 | $542.08 | $846.72 |
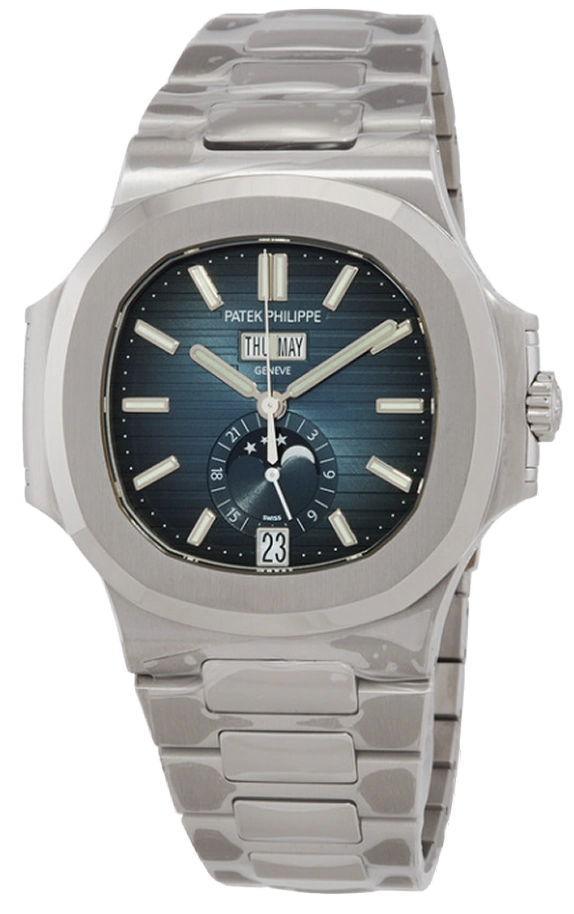
| Patek Philippe Nautilus | $130,000 | $1,467.93 | $2,293.20 |
*Coverage amount is based on insured value. Annual premium range is an estimate; exact premiums depend on your location and specific policy details.
BriteCo offers standalone watch insurance for luxury and high-value timepieces with no maximum insured value and zero deductibles. We cover your watch at its insured value, whether you own one watch or a full collection.
Whether you own one watch or an extensive collection, BriteCo covers your timepieces for their full value with worldwide protection against theft, loss, accidental damage, and mysterious disappearance.
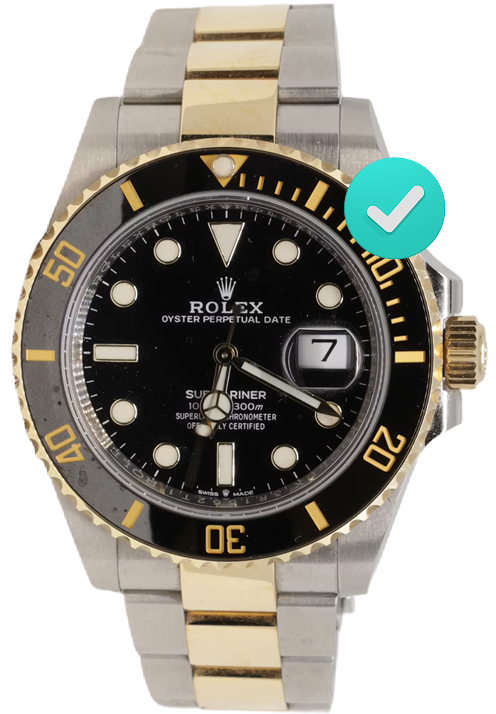
For luxury watches, look for a standalone policy with insured value coverage, a zero or low deductible, worldwide protection, mysterious disappearance coverage, and claims that stay off your homeowners record. BriteCo offers each of these.
Watch insurance is sold by specialty insurers, by jewelry insurers, and as riders on homeowners policies. When you compare providers for a luxury watch, check these points:
a separate policy instead of a rider on homeowners insurance.
including theft and loss while traveling.
BriteCo carries zero deductibles on covered claims.
BriteCo claims aren’t reported to CLUE or A-Plus.
not every policy includes all four.
BriteCo offers online claims from start to finish, with a claims coordinator for support.
BriteCo’s policies are backed by Glencar Insurance Company, an A+ rated carrier by AM Best, and Hannover Re, our investor and reinsurance partner, assuring strong financial security and reliability.
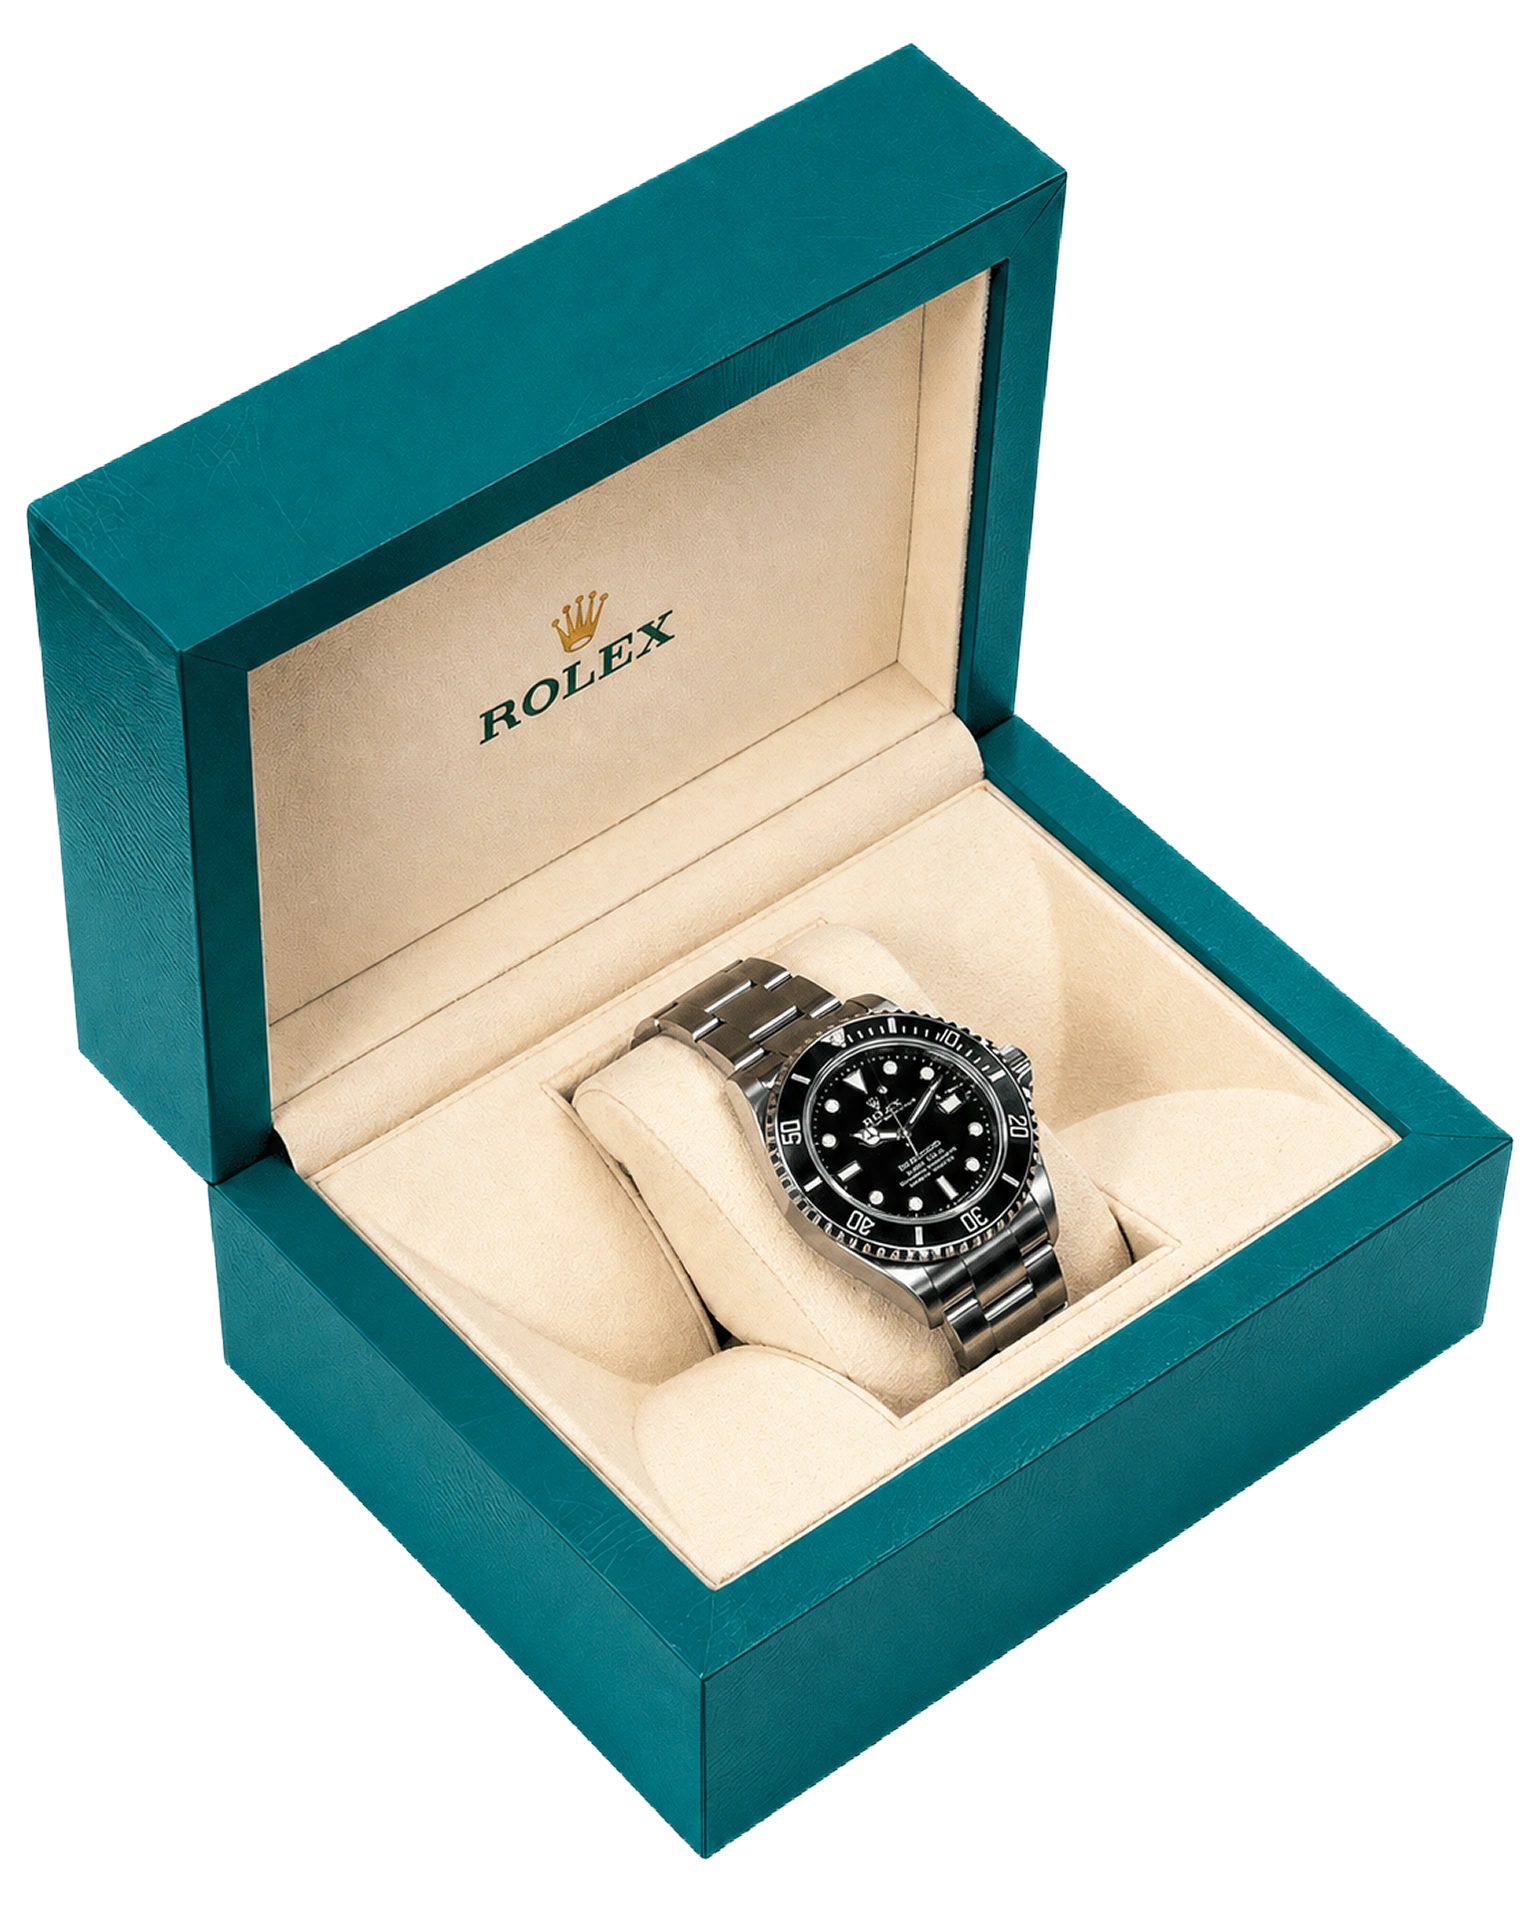
BriteCo insures Rolex, Patek Philippe, Audemars Piguet, Omega, TAG Heuer, Cartier, Breitling, Chopard, Vacheron Constantin, Citizen, Ulysse Nardin, and more, including new, vintage, and pre-owned pieces.
BriteCo is a licensed insurance agency in all fifty states and the District of Columbia, and is trusted by 3,500+ independent jewelers nationwide.
See what policyholders say on the BriteCo reviews page.
Most homeowners policies sub-limit jewelry and watches at $1,000–$2,000 per item, regardless of what you own. Some allow a rider that schedules specific items, which gives you better coverage, but the claim still runs through your homeowners policy.
This matters because a homeowners claim can significantly affect your renewal premium. A standalone watch policy from BriteCo keeps the claim off your homeowners record entirely.
Renter’s and condo policies have the same sub-limit problem. The building’s structure is covered by someone else’s policy; your personal property is on you, and the default limits weren’t designed for luxury watches.
If you have 1–2 watches valued at $5,000 or less and already have a good homeowners policy with a low deductible, adding a rider may be enough.
If any single piece is worth more than your homeowners sub-limit, a standalone policy from BriteCo makes the most sense.

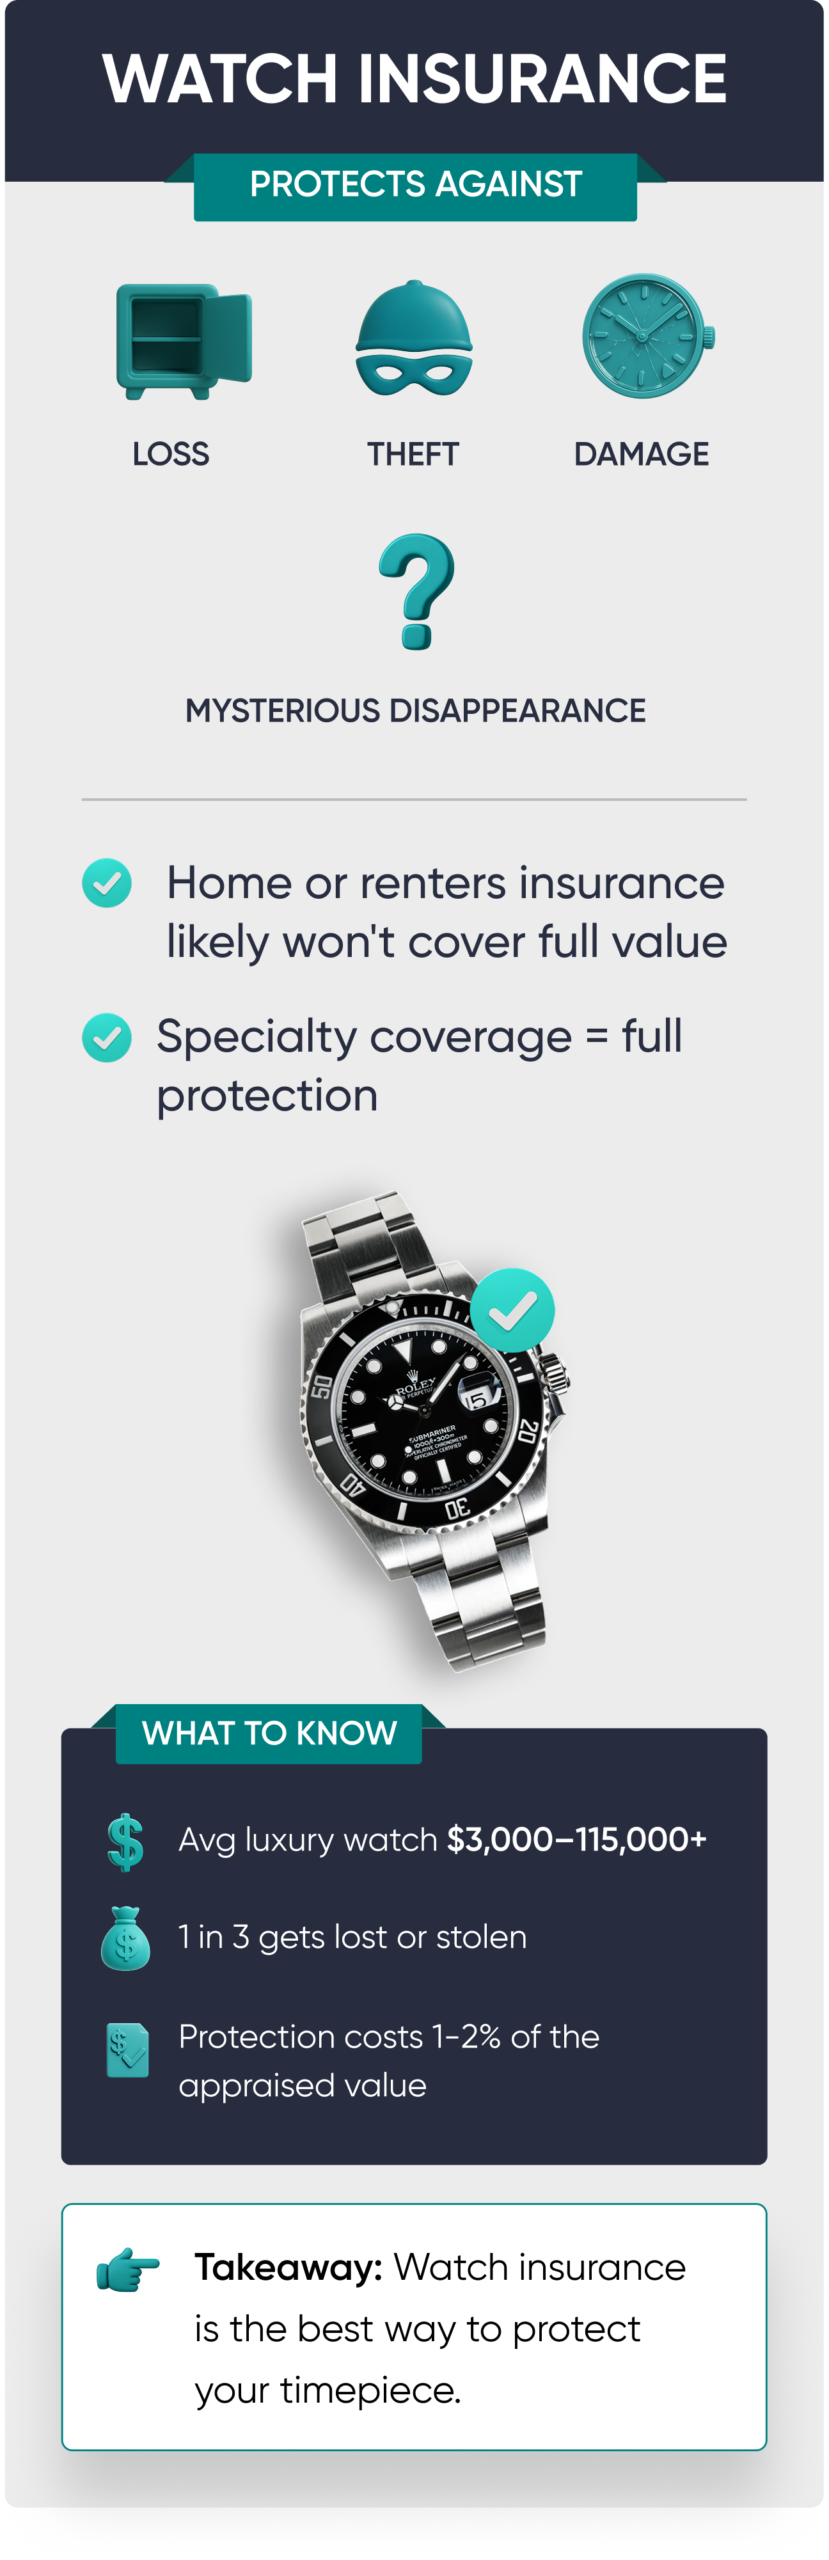
A manufacturer’s warranty typically covers defects only. It does not cover drops, theft, or unexplained loss. That is what watch insurance is for.
A warranty won’t help if you drop your watch on a tile floor, have it snatched in a parking lot, or find it gone with no explanation.
Watch insurance does not cover intentional damage or losses from war, nuclear events, government seizure, or confiscation. Policies also require proof of ownership and, for high-value pieces, a current appraisal.
A receipt from 8 years ago may not be enough if the watch has appreciated significantly since then. Coverage requirements vary by policy, so review policy specifics and exclusions when comparing watch insurance coverage.
Contact BriteCo as soon as the loss happens. You can file a claim easily online. Waiting creates complications.
If the watch was stolen, file a police report. You’ll need the report number for the claim.
Pull together your documentation: appraisal, proof of ownership, photos, and purchase receipt.
For theft and mysterious disappearance claims, describe when and where you last had the watch.
BriteCo will assign a claims handler who will contact you directly and keep in touch as you go through the repair or replacement process to make sure you’re happy with the result.
BriteCo insures Rolex, Patek Philippe, Audemars Piguet, Omega, TAG Heuer, Cartier, Breitling, Chopard, Vacheron Constantin, Citizen, Ulysse Nardin, and more. That includes new pieces, vintage pieces, and pre-owned pieces.
Worldwide coverage
Zero deductibles on covered claims
Monthly payment options
Online claims, start to finish with human backup
5-star rated customer service
Trusted by 3,500+ independent jewelers nationwide

BriteCo Watch Insurance costs about 1% to 2% of the watch's insured value per year. For a $15,000 watch, BriteCo premiums run roughly $150 to $300 annually. Location, value, and storage affect your exact price.
Only up to a point. Most standard homeowners insurance policies only cover watches up to a sub-limit of $1,000 to $2,000 per item. Watches worth more than that may not be fully covered. You can add a scheduled rider to your homeowners policy, but filing a claim could increase your homeowners premium. A standalone policy from BriteCo provides full coverage at an affordable price.
For pieces above a certain value, yes. An appraisal from a reputable watch or jewelry store or independent appraiser establishes the insured value. This helps protect you in case of loss or theft. Without a current appraisal, the claim payout could fall short of the watch's actual market value.
Mysterious disappearance means you don't know when, where, or how your watch went missing. There's no evidence of theft and no specific incident to explain the loss. A standalone watch insurance policy covers mysterious disappearance, while most standard homeowners policies do not.
Yes. The purchase channel doesn't affect coverage eligibility. What matters is a current appraisal reflecting today's market value. In some cases, the original sales receipt from the initial owner may suffice, though an appraisal from a reputable watch dealer is preferred.
No. BriteCo insures luxury watches, high-value timepieces, and full collections with no maximum insured value. Your watch is covered for its full appraised value, with a zero deductible and worldwide protection against theft, loss, accidental damage, and mysterious disappearance.
Yes. BriteCo covers theft from your home, your car, or while traveling, with worldwide protection.
Intentional damage and losses from war, nuclear events, government seizure, or confiscation are not covered. Policies also require proof of ownership and, for high-value pieces, a current appraisal.