Renters insurance may include jewelry coverage, but specific coverage exclusions, personal property coverage sublimits, deductibles, and other factors will ultimately impact what your policy may actually pay out in the event of a potentially covered claim.
Before assuming you’re covered, answer five questions:
- What caused the loss I’m trying to claim?
- What is my jewelry sublimit?
- What deductible applies (if any)?
- Is the item scheduled?
- And how does the policy value a covered loss?
Let’s check in with BriteCo founder and CEO Dustin Lemick to find out how to tell if your renters insurance covers jewelry, potential covered losses, what you might expect in terms of a claim payout, and more.
What You Will Learn
- How to Check Whether Your Renters Policy Covers Your Jewelry
- Renters Insurance Jewelry Coverage by Scenario
- What If Your Jewelry is Worth More Than Your Renters Policy Limit?
- How Much Could Your Renters Policy Actually Pay for a Jewelry Claim?
- Standard Renters Coverage Vs. Scheduled Jewelry Vs. Stand-Alone Jewelry Insurance
- Could a Jewelry Claim Affect Your Property-Insurance History?
- If Your Renters Coverage Falls Short, What Should You Do Next?
- Frequently Asked Questions
- Final Takeaway — “Jewelry Is Covered” Is Only the Beginning
How to Check Whether Your Renters Policy Covers Your Jewelry
Inspect your actual renters insurance policy and contract, and look at the following factors to determine if and to what degree your policy covers your jewelry:
| Check Your Policy For… | Ask… |
|---|---|
| Personal property coverage | Is jewelry included? Is it excluded? |
| Covered causes of loss | Is your specific event a covered peril, per the policy? |
| Special jewelry limits | Is there a category or theft sublimit? |
| Deductible requirements | What comes out of the claim? |
| Scheduling requirements | Is the item individually listed/scheduled on your policy? |
| Settlement methods | Does the policy cover your replacement cost, actual cash value, or another value? |
“Coverage in renters policies can be quite limited,” Lemick says. “There can be large deductibles that don’t really make sense for a jewelry insurance policy. And mysterious disappearances might not be covered.”
After you review your coverage limit for jewelry, consider purchasing additional coverage if your jewelry’s value exceeds that limit.
Check Whether the Cause of Loss Is Covered
A standard renters insurance policy may offer personal property coverage that applies to jewelry, but you’ll want to be certain of the policy’s covered perils. Just because a piece of jewelry is covered, that doesn’t mean that it’s covered under all circumstances. A piece of jewelry can disappear or break in a way that invalidates a claim.
Find the Jewelry Sublimit
A policy may only pay out a certain amount for jewelry claims, depending on how much coverage your policy offers. As such, check your policy for its:
- Overall personal-property limit
- Jewelry-specific special limit
- Theft-specific jewelry limit
- Per-item scheduled limit
That will inform you of how well your jewelry is covered and whether or not you need additional coverage to match your piece’s or collection’s total value.
Check Whether the Piece Is Scheduled
Sometimes, jewelry is “scheduled” as a secondary part of your broader renter’s policy. Scheduled personal property coverage specifically identifies unique, valuable items and can increase limits or broaden protection for those scheduled items, depending on the policy terms.
Check How the Policy Values a Covered Loss
Lastly, look at how the renters policy values a covered loss and how it will affect your claim payment.
If the policy covers your item’s full replacement cost, it means you’ll receive a claim payout suitable for fully replacing your item with a brand-new piece of original like kind and quality.
If, however, the policy only covers your item’s actual cash value (ACV), you’ll only receive the amount that your exact, specific item is worth, including depreciation, any damage, etc. As such, the claim payment may be lower.
Renters Insurance Jewelry Coverage by Scenario
Certain losses such as theft are more likely to be covered by renters insurance, but it may be less likely to cover claims related to damage or mysterious disappearance.
| Potential Scenario | Will Standard Renters Insurance Coverage Cover It? | What to Check for on Your Policy |
|---|---|---|
| Ring stolen from apartment | Potentially covered | Theft peril, jewelry sublimit, deductible |
| Jewelry stolen from hotel/car | Potentially covered | Off-premises coverage + limits |
| Ring simply lost | Probably not | Accidental loss / mysterious disappearance wording in the policy |
| Ring disappears with no explanation | Probably not | Mysterious disappearance coverage |
| Stone falls out | Probably not | Accidental damage/loss coverage vs. scheduled coverage |
| Ring dropped down drain | Probably not | Accidental-loss coverage |
| Jewelry damaged by covered fire | Potentially covered | Covered peril, limit, and settlement basis |
| Jewelry value exceeds sublimit | Yes, but you’re at risk of being underinsured | Scheduling or specialty coverage |
My Engagement Ring Was Stolen From My Apartment
If your renters policy covers jewelry theft, then you’re covered if a ring is stolen from your apartment. That doesn’t mean, however, that your ring’s full value will be covered.
Check your policy’s limit for stolen jewelry, as well as its deductible and the ring’s documented value. Then, submit your claim, adhering to your policy’s documentation requirements, such as requirements for a police report, witness statement, etc.
I Lost My Ring While Traveling
Accidental loss and mysterious disappearance are less likely to be covered by standard renters insurance. If you have off-premises theft coverage, and your ring was undoubtedly stolen from a hotel room, you may be covered. However, if the ring has simply disappeared during the course of your travels, the claim may fall outside standard coverage.
A Stone Fell Out
Whether or not a renters policy will cover the loss of a stone will depend on the cause of the loss.
Was it due to…
- Sudden accidental damage?
- General wear and tear?
- A maintenance problem?
- Or simply an unexplained event?
Check your individual policy to see what might be covered.
I Dropped My Ring Down a Drain
Dropping a ring down a drain is the kind of loss a standard renters policy may not treat as a covered peril. However, if you have broader floater coverage, it may treat this as a covered accidental loss, depending on the terms.
What If Your Jewelry is Worth More Than Your Renters Policy Limit?
If the documented appraised value of a piece of jewelry exceeds your policy’s jewelry sublimit, a covered claim can still leave you paying a large amount out of pocket for a replacement.
Your jewelry’s value – Your policy’s available jewelry coverage = The potential coverage gap
Standard renters coverage may not offer enough coverage for certain high-value items. Evaluate additional coverage when needed, such as for engagement rings.
“At BriteCo, we will cover up to 125 percent of the total appraised value,” Lemick says.
Document the Jewelry’s Value
It’s important to keep your jewelry’s documented value up to date and accurate, to gauge whether or not you have sufficient coverage. Keep on file your:
- Receipt
- Photographs of the piece
- A grading report if applicable
- A current jewelry appraisal
- Documented identifying details
Not only will these documents allow for more adequate coverage, but they’ll also be crucial for supporting any future insurance claims.
High-Value Engagement Rings Need a Separate Limit Check
Expensive jewelry such as an engagement ring may require additional coverage, but not always.
Does the ring’s current documented replacement value fit comfortably within the protection already available under your renters policy? If the full value is not covered, separate coverage is something to consider.
How Much Could Your Renters Policy Actually Pay for a Jewelry Claim?
Your potential claim payment will depend on the covered loss, your applicable jewelry limit, the item’s documented value, your policy’s settlement method, and your deductible.
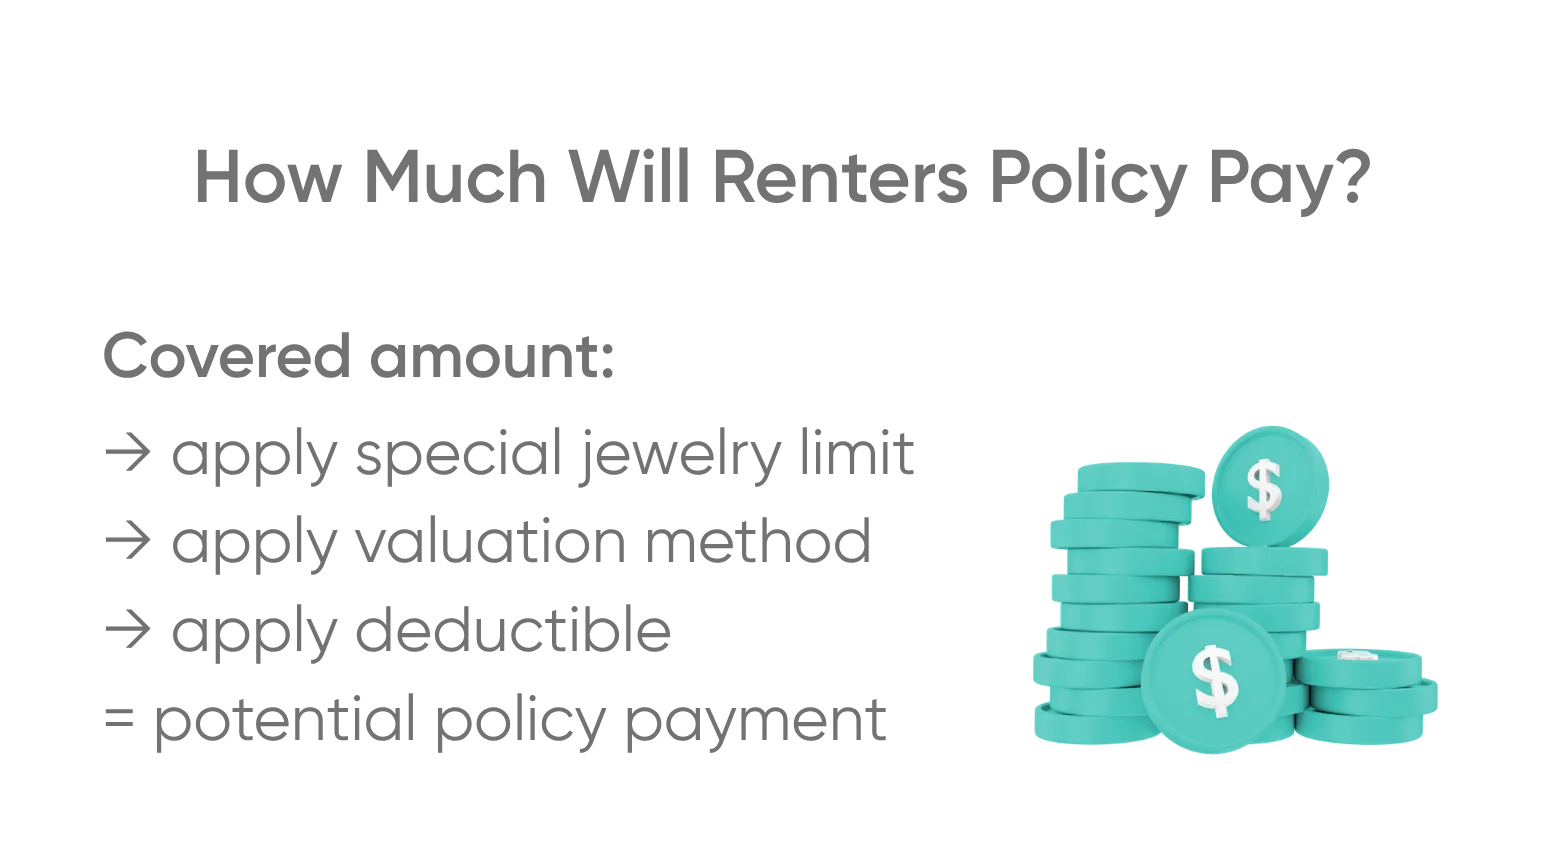
Actual claim calculations are controlled by your policy language and the insurer.
Replacement Cost Vs. Actual Cash Value Can Change the Result
Again, remember that whether your insurer covers your piece’s replacement cost or actual cash value will impact your claim payout. Replacement-cost coverage pays the actual cost to replace your covered belongings without a depreciation deduction, while actual-cash-value coverage deducts depreciation.
Standard Renters Coverage Vs. Scheduled Jewelry Vs. Stand-Alone Jewelry Insurance
| Option | How It Works |
|---|---|
| Standard renters policy | Broad personal-property protection with policy-specific limits |
| Scheduled jewelry rider or jewelry floater on a standard policy | Adds item-specific protection to or alongside the property policy |
| Stand-alone jewelry insurance policy | Separate policy designed specifically around jewelry risks |
What Standard Renters Coverage Does
Standard renters insurance offers personal property coverage, but with policy-specific special limits; it covers some of the main concerns you may have surrounding your jewelry (theft, etc.), but the coverage won’t be as comprehensive. However, it is convenient and already built into your existing coverage.
What Scheduling Jewelry Changes
Scheduling is essentially purchasing extra coverage on your existing policy; this additional insurance coverage can change or expand item-specific limits and the types of covered events.
What Stand-Alone Jewelry Insurance Changes
A separate jewelry policy may offer broader protection designed around theft, loss, accidental damage, and/or mysterious disappearance depending on provider and policy.
Could a Jewelry Claim Affect Your Property-Insurance History?
When making a jewelry claim with your renters or homeowners insurance company, it may negatively impact your insurance history, leading to higher premiums or policy non-renewal in the future.
That’s an extra cost you don’t want to deal with, especially as BriteCo claims-reporting research recently found that 75% of insured clients have experienced homeowners premium increases in the last year alone!
Opting for a stand-alone jewelry insurance policy can help you avoid this.
Don’t let a jewelry claim become a homeowners insurance issue. During the claims process, BriteCo does not report jewelry claims to CLUE or A-PLUS, the loss-history databases used in property-insurance underwriting. Before you buy jewelry insurance, ask the provider if and exactly where your claim history is reported.
If Your Renters Coverage Falls Short, What Should You Do Next?
If your current renters insurance is not enough to completely cover your jewelry’s full value, explore your other coverage options and add coverage for extra protection from the risks that matter most to you.
| Gap in Your Existing Insurance | What to Ask Next |
|---|---|
| Jewelry limit too low | Can I schedule the item or use stand-alone coverage? |
| Deductible is too high | Would item-specific coverage offer a lower deductible? |
| Accidental loss is excluded | Which alternatives cover loss? |
| Mysterious disappearance is excluded | Which alternatives explicitly include mysterious disappearance? |
| Coverage away from home is limited | Is worldwide protection available? |
| Jewelry claims affect property policy | Would a separate specialty policy avoid that reporting relationship? |
Compare renters vs. homeowners vs. specialized insurance for your jewelry.
If you decide your renters policy leaves a meaningful gap in coverage, explore the price of additional protection based on your specific item’s value and coverage needs.
See how much jewelry insurance costs.
Frequently Asked Questions
Does Renters Insurance Cover Jewelry?
Yes, renters insurance may cover jewelry under personal property coverage, but whether or not a claim is accepted and what is paid out will depend on cause of loss, jewelry-specific limits, your deductible, and scheduling status. Sometimes, additional coverage is needed to fully protect jewelry.
Does Renters Insurance Cover Stolen Jewelry?
Theft from your rental property may be covered by your renters insurance, but jewelry may still come with a separate special sublimit and your deductible may still apply.
Does Renters Insurance Cover a Stolen Engagement Ring?
Potentially, yes, renters insurance may cover a stolen engagement ring if it was stolen from the property you’re renting, but the policy may not cover the ring’s full value. Whether or not a claim is accepted, and how much your policy pays out, is subject to the theft coverage, jewelry limit, deductible, and documentation in the actual policy.
Does Renters Insurance Cover Jewelry Stolen While Traveling?
Many renters policies extend covered perils off-premises, so theft away from home may qualify as a claim, subject to the policy’s limits.
Does Renters Insurance Cover a Lost Ring?
A ring that is simply lost or mysteriously disappears is often not covered under standard property insurance; check your actual policy wording to be sure.
Final Takeaway — “Jewelry Is Covered” Is Only the Beginning
“The right question isn’t only whether renters insurance includes jewelry” Lemick says. “It’s whether your specific loss is covered, whether the jewelry sublimit is high enough, what deductible applies, and whether the policy would actually replace the value you have at risk.”
Check your policy’s covered losses, special limits, deductible, scheduling requirements, and valuation method to determine how your jewelry is insured and how much protection you have.
If those five checks reveal a meaningful gap in coverage, compare that gap against dedicated jewelry coverage before deciding how to insure the piece. Get your BriteCo jewelry insurance quote in minutes, right now.
Related Article:
When to Insure an Engagement Ring
Appraisal Tool:
The Easiest Way to Get a Professional Jewelry Appraisal Valuation!
UP NEXT: Shopping for Gaming Computer Insurance? Here’s What You Need to Know
Author